TL;DR: The Philippines property market sits at a point where the structural drivers for tourism-linked real estate are stronger than the perception of the market among foreign investors. International arrivals are recovering toward pre-pandemic levels in key leisure destinations. Supply constraints in environmentally protected áreas are preventing the oversaturation that occurred in some Thai and Balinese markets. The legal framework for foreign investment via long-term leasehold is established and registered. The gap between perceived risk and actual investment performance is the thesis.
Why the Philippines Gets Underweighted by Foreign Investors
The standard allocation of foreign capital in Southeast Asian real estate goes to Thailand, Bali, and to a lesser extent Vietnam. The Philippines participates in conversations but underperforms its fundamentals in terms of actual capital deployed from overseas.
The reasons are understandable but largely historical. The archipelago’s logistics complexity, the mixed experience of investors in less-developed provinces before tourism infrastructure caught up, and the incomplete picture that Western media carries of a country with strong pockets of development surrounded by áreas that genuinely require more caution.
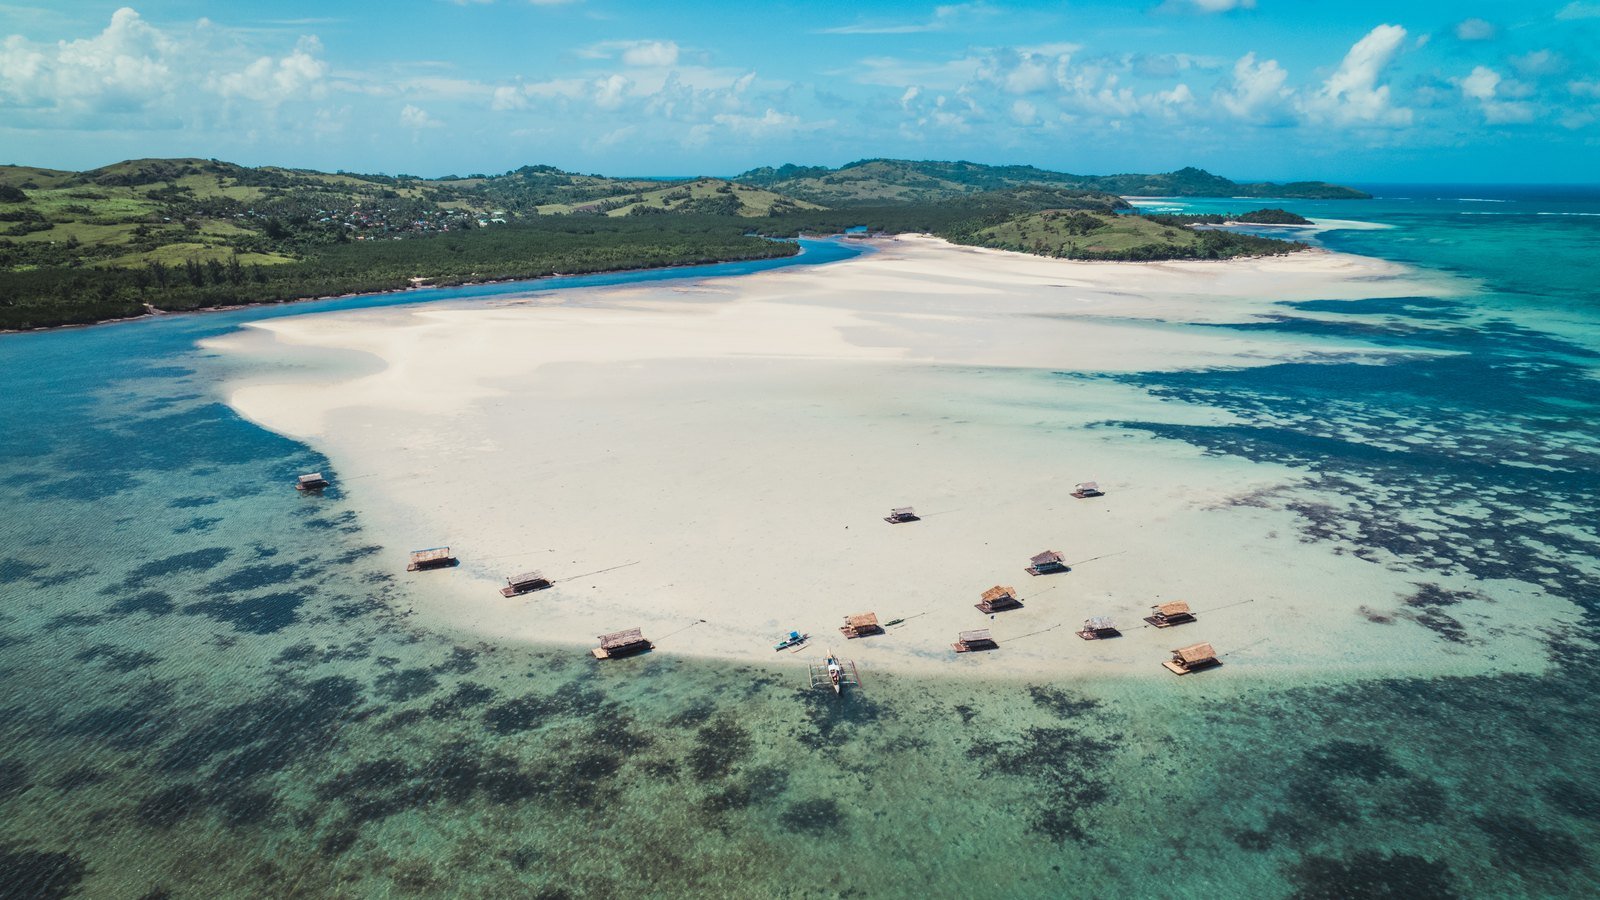
The more honest framing is that the Philippines is not one market. Palawan and Camarines Sur are not representative of every part of the country, any more than the Costa del Sol is representative of all of Spain, or Bali of all Indonesia. The investment case rests on specific destinations with specific characteristics: functioning infrastructure, documented tourism demand, legal clarity, and supply constraints that protect value.
The Structural Drivers: What Supports the Investment Case
International tourism recovery. Philippine international arrivals collapsed during the pandemic and have been recovering since 2022. Department of Tourism data for 2024-2025 shows arrivals in Palawan and Camarines Sur tracking toward pre-pandemic levels, with El Nido and San Fernando as specific beneficiaries. The base of demand is rebuilt; the supply of quality accommodation has not grown proportionally.
Domestic tourism depth. Unlike some island economies that depend almost entirely on international arrivals, the Philippines has a domestic market of 115 million people with rising disposable incomes. San Fernando sits in Camarines Sur, with Naga City and its Pili airport (a roughly 50-minute flight from Manila) plus road access via the Maharlika Highway, so it draws domestic tourism through a regional hub regardless of international travel patterns. This base load insulates against the full-cyclical swings that purely international destinations experience.
UNESCO and DENR supply constraints in Palawan. El Nido sits within the El Nido Taytay Managed Resource Protected Área, subject to DENR (Department of Environment and Natural Resources) Environmental Compliance Certificate requirements that limit new development approvals. New supply in El Nido must navigate regulatory processes that do not exist in unprotected áreas. This structural limitation on future supply supports existing inventory values.
The barangay-level infrastructure gap is closing in key destinations. San Fernando, in the Naga City corridor of Camarines Sur, has fibre broadband from PLDT and Converge ICT, and Naga’s Pili airport gives the área reliable domestic air connectivity. El Nido has improved domestic air connectivity and electricity reliability. The gap between perception (Philippines = poor infrastructure) and reality (specific destinations with functional urban infrastructure) is closing.
Currency dynamics. The Philippine peso has maintained relative stability against major currencies over medium-term horizons. For an investor earning in GBP, USD, EUR, or AUD, entry prices denominated in PHP at current exchange rates represent favourable purchasing power. Long-term structural convergence of Philippine wages and prices toward regional norms provides a tailwind for property values in local currency terms.
The Legal Reality for Foreign Buyers
Foreign investors cannot own land in the Philippines under Article XII Section 7 of the 1987 Constitution. This is a hard constitutional restriction, not a policy that changes with governments.
The operative legal mechanism is the Republic Act 7652 long-term leasehold. The mechanics are straightforward: a 99-year leasehold, registered as a Transfer Certificate of Title (TCT) at the Registry of Deeds. The registered leasehold is a real property right, not just a contractual right. It can be sold, inherited, and used as collateral in some financial arrangements.
What the leasehold provides in practice: legal certainty for a 99-year horizon, registered title in the Philippine property registry, the right to rent the property to third parties, use rights for the owner, and transmissibility to heirs.
The condominium exception allows outright freehold ownership of units in registered condominium buildings, subject to a cap of 40% of total units in the building being foreign-owned. This is the route for urban condominium investments in Metro Manila and other cities with high-rise inventory. For villa-type properties on coastal land, the leasehold is the standard legal structure.
How the Numbers Work: Yield Profile for Tourism-Linked Property
The yield on managed villa rentals in Filipino coastal tourism destinations reflects a market where:
Short-term rental platforms (Airbnb, Booking.com, Agoda) have strong demand in peak season and meaningful off-season occupancy driven by domestic tourism.
Management fees for full-service operators run 25% to 35% of gross revenue.
Operating costs (housekeeping, maintenance, utilities, consumables) add approximately 15% to 20% of gross revenue.
Net yield on a Villa Standard in San Fernando at 109,900 EUR, operating at 60% annual occupancy with an average nightly rate of 130 EUR, is approximately 13.4% on the investment.
Net yield on a Loft in El Nido at 149,900 EUR, operating at 60% occupancy at 160 EUR per night, is approximately 12.5% on the investment.
These figures are illustrations of the cost structure, not guarantees. Actual performance depends on the operator’s track récord, the specific property’s review profile on platforms, and seasonality. El Nido has stronger peak-season demand but more pronounced low-season patterns than San Fernando, which benefits from year-round domestic demand.
The comparison point for any investor should be the net yield available on equivalent-risk property investments in their home market. In the UK, Spain, or Australia, net residential rental yields in coastal leisure destinations typically range from 3% to 6% after costs, with significantly higher entry prices per square metre.
The Risks: Where the Picture Is Less Clean
Concentration risk. A single property in a single market is undiversified. If that market underperforms (natural event, regulatory change, shift in tourism flows), the investor has no hedge. This is a general real estate risk, not specific to Philippines, but worth stating.
Currency volatility. Rental income generated in PHP converts to investor currency at market rates. Short-term PHP volatility adds noise to returns. Over a 10-year horizon, the impact tends to moderate, but it is a real short-term consideration.
Operator risk. The quality of the managed rental operator determines a meaningful portion of actual return. An operator with poor platform management, high vacancy periods, or inadequate maintenance will underperform a well-run one even with identical property characteristics. Due diligence on the operator is as important as due diligence on the property.
Regulatory evolution. Philippine tourism policy, environmental regulations in protected áreas, and short-term rental regulation via DOT accreditation can evolve. The current environment is relatively permissive for managed rentals in designated tourism zones. Changes to that environment would affect yield profiles.
Access and logistics. The Philippines is further from Europe than Thailand or Bali. Owner use of the property requires longer travel time. For investors whose primary motivation is personal use rather than yield, this is a meaningful consideration.
What the Managed Rental Model Solves
The managed rental model, where a professional operator handles all aspects of letting and maintenance, addresses the main operational challenge of investing in a property you cannot physically oversee.
Full-service operators handle platform listing and management, guest reception and checkout, housekeeping between stays, routine maintenance, and monthly or quarterly reporting to the owner. The investor receives a net transfer after costs and management fees.
Owner use rights (typically 30 to 60 nights per year with advance notice) allow the owner to use the property during periods in the Philippines without disrupting the rental programme’s commercial viability.
The economic logic for the investor: deploy capital in an asset with strong yield characteristics, receive passive income managed by a professional operator, retain personal use rights, and benefit from potential capital appreciation over the leasehold term.
Frequently Asked Questions
Is this a new market or an established one?
San Fernando sits in Camarines Sur, home to the CamSur Watersports Complex, a world wakeboarding reference that has drawn watersports tourism and hosted international championships since the mid-2000s. El Nido has been on international tourist itineraries for over two decades. The managed rental programme for foreign investors is newer in structure, but the underlying tourism market and property operations are established, not speculative.
How does the Philippines compare to Bali or Thailand for this type of investment?
The legal framework is superior to Bali (no nominee structure ambiguity) and comparable or better than Thailand (99-year statutory leasehold vs 30-year contractual). Net yields are higher than typical Bali or Thai beachfront properties at equivalent quality. Supply constraints in El Nido are stronger than in most Thai or Balinese markets. The trade-off is greater distance from Western markets and a smaller existing community of foreign property owners.
What is the minimum investment?
Villa Standard in San Fernando from 109,900 EUR, with a payment plan starting from 1,109 EUR per month over 60 months for qualified buyers. El Nido Loft from 149,900 EUR.
How are rental income and capital gains taxed?
Rental income generated in the Philippines is subject to Bureau of Internal Revenue (BIR) withholding on gross receipts for non-residents. In the investor’s home country, rental income is declarable as foreign source income. UK investors use SA106 to declare foreign income; Australia uses FITO provisions; Spain uses the double taxation treaty with the Philippines. Specific tax advice from a qualified accountant in your home jurisdiction is recommended.
How does the due diligence process work for a remote purchase?
The standard process includes: engagement of an independent Philippine lawyer (not the developer’s lawyer), title chain verification at the Registry of Deeds, review of the lease agreement and management contract, and execution via power of attorney if not physically present. Most international buyers complete the transaction without being in the Philippines, coordinating the signing phase remotely with a trusted Philippine legal representative.
Next Steps
For property specifications, availability by location and type, and the managed rental programme terms, contact the Land of Nomads team.
[PENDIENTE: Contact or enquiry URL]
Sources
- Philippine Department of Tourism (DOT): international and domestic visitor data, Camarines Sur and Palawan, 2023-2025.
- Land Registration Authority (LRA), Philippines: leasehold registration procedures under RA 7652.
- Republic Act 7652, Philippines: Investors’ Lease Act, 1994.
- DENR (Department of Environment and Natural Resources): Environmental Compliance Certificate requirements, El Nido Taytay MRPA.
- UNESCO Man and Biosphere Reserve Programme: El Nido Taytay Managed Resource Protected Área designation.
- Bangko Sentral ng Pilipinas (BSP): peso exchange rate historical data and foreign investment repatriation rules.
- Agoda Travel Insights: occupancy and ADR data, Camarines Sur and El Nido, 2024-2025.
- Airbnb Data: occupancy benchmarks, Palawan and Camarines Sur, 2024.
- Philippine Statistics Authority (PSA): domestic tourism and economic data.
- CamSur Watersports Complex: operational and international wakeboard event data.